Banking Solutions

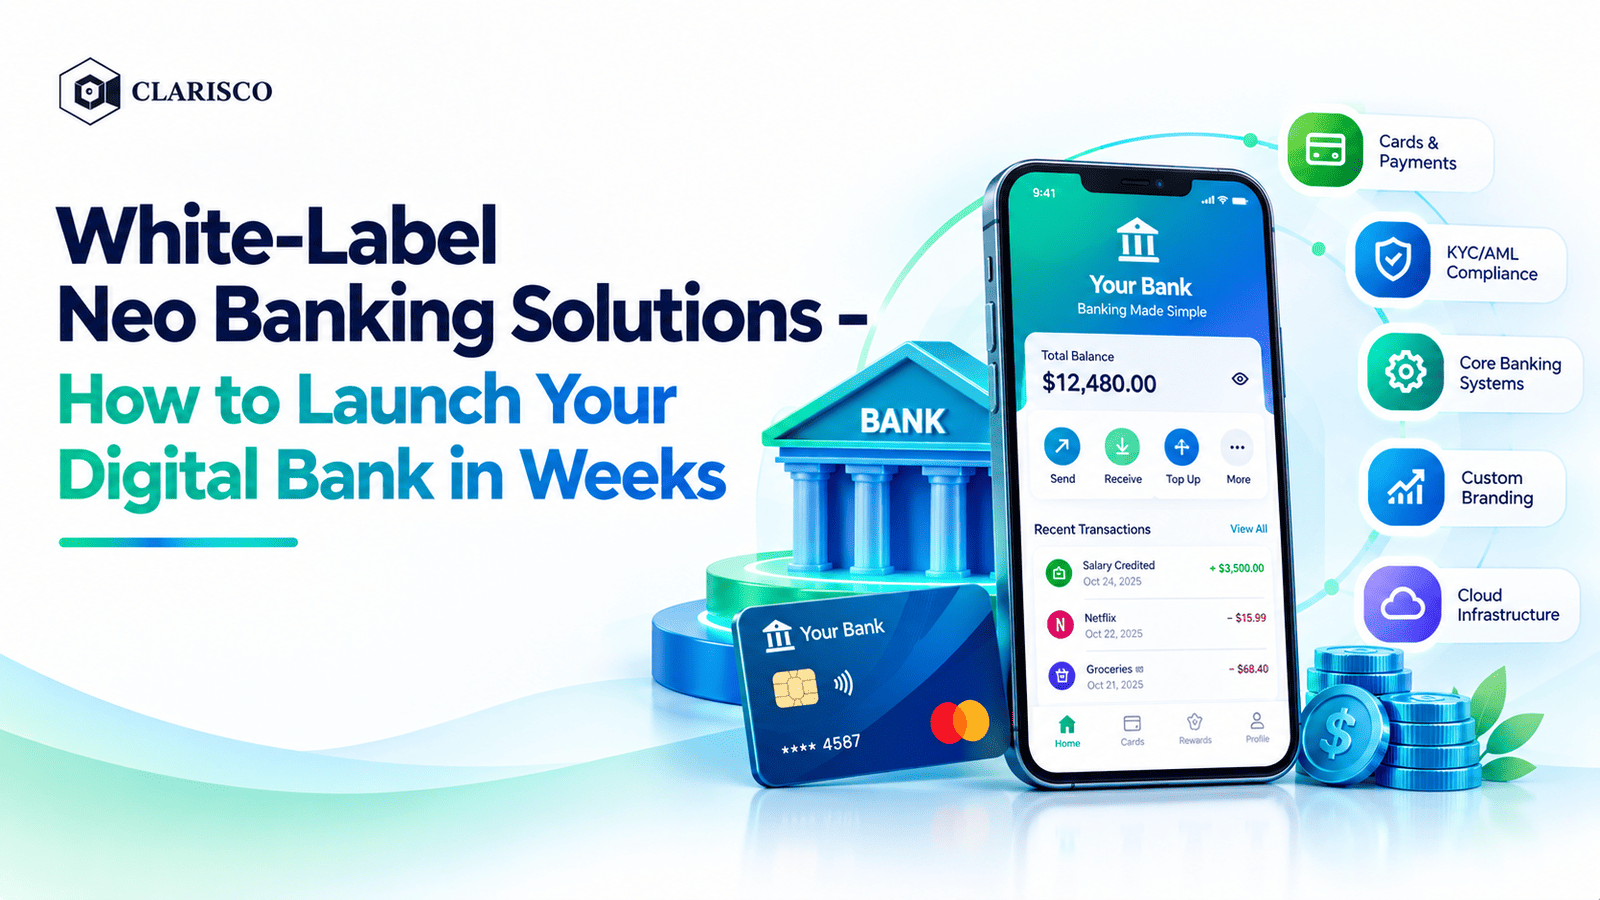
White-Label Neo Banking Solutions - How to Launch Your Digital Bank in Weeks

Share:
Founder

Author

Priyadharshini Suriyanarayanan
Founder Founder

Table of Contents

Author's Bio
Founder
Priyadharshini Suriyanarayanan
Founder Founder

The Founder and CEO of Clarisco Solutions Private Limited, a product engineering company focused on AI and Web3 development.

With over 12 years of experience in AI, blockchain, and enterprise software, she has led more than 650 product launches across categories including crypto exchanges, DeFi protocols, AI agents, generative AI products, tokenisation platforms, and NFT ecosystems.

She specializes in AI-driven Web3 product engineering and has built a reputation for delivering systems that work in production environments.

Contact us
...
✨ AI Summary ✨
  • The global neobanking market is expected to reach $578 billion by 2027, growing at a 46.5% CAGR. As per reports, 350 million people around worldwide use neobanks today.
  • A white-label neobank solution is an established digital banking system that includes accounts, cards, payments, compliance, and customer onboarding.
  • There are various types of neobanks available, including consumer digital banks, business neobanks, crypto-integrated neobanks, and lending-first neobanks.
  • The cost to develop a digital bank using white-label neobanking software starts from $50,000 and goes up to $150,000.

The global neobank market is projected to reach $578 billion by 2027, growing at a 46.5% CAGR.

350 million people worldwide use neobanks today, up from 146 million in 2021. Millennials and Gen Z make up 78% of that base. Revolut hit 68.3 million retail customers with $6 billion in revenue and $67.5 billion in customer balances.

These neo banking solutions are revolutionizing the FinTech industry with a faster and more accessible approach than traditional banks. A white-label neobank solution compresses the development window to weeks, that a business deploys under its own brand. This guide covers everything about white-label neobanking software.

What Is a White-Label Neo Banking Software?

A white-label neo banking solution is an established digital banking system that includes accounts, cards, payments, compliance, and customer onboarding, which a company licenses, brands, and implements as its own offering without building the underlying foundation from scratch.

The ‘white label’ part means the technology is invisible to the end customer. The user views the brand, colors, and app name. The fundamental banking system, card issuance framework, KYC/AML compliance structure, and payment networks operate behind the scenes, managed and upgraded by the software vendor.

This is fundamentally different from becoming a bank. In most jurisdictions, launching a white-label neobank does not necessitate a complete banking license. The business that is deploying usually functions under a Banking-as-a-Service (BaaS) arrangement with an authorized partner bank, which manages deposits, provides cards, and upholds the compliance relationship.

Types of Neo Banking Solutions

The neo banking platform determines the account structure, compliance requirements, payment features, and the revenue model. Clarisco builds all five types, starting from the same core and configuring it for each deployment's specific market.

  1. Consumer Digital Bank

Built for individual retail customers, a full-featured digital bank account with debit cards, P2P transfers, bill payments, savings goals, and spending analytics. The standard neobank model. Examples include Chime, Monzo, and N26.

  1. Business Neobank

Built for SMEs, freelancers, and startups who need business accounts, multi-user access, invoicing tools, payroll, expense management, and real-time financial reporting. Designed with various KYB compliance processes, multi-signature account functions, and ERP/accounting integrations.

  1. Crypto-Integrated Neobank

This platform combines conventional banking elements, including debit cards with a crypto wallet. It also allows users to store, purchase, sell, and utilize both fiat and cryptocurrencies within one mobile/web application. PayFi-enabled platforms in this category are generating strong adoption among younger demographics.

  1. Lending-First Neobank

Built around a loan management software core including personal loans, BNPL, SME credit, or micro-lending with banking features layered on top. Loan origination, credit scoring, repayment scheduling, collections, and interest accrual management are the primary technical components.

  1. White Label BaaS Platform

A neobank platform deployed as infrastructure for other businesses by allowing brands, retailers, telecom operators, or HR platforms to launch financial products under their own brand.

Must-Have Features of a White-Label Neobank Software

None are optional for a deployment that will handle real customer deposits, real card transactions, and real regulatory inquiries.

  • Core Account Management

Multi-currency account creation, virtual IBAN assignment, real-time balance tracking, account statement generation, and transaction history.

  • Card Issuance and Management

Virtual and physical debit card issuance through BIN sponsorship, spend controls, card freeze/unfreeze, and real-time push notifications on every transaction.

  • Multi-Rail Payment Infrastructure

Domestic transfers via ACH (US), SEPA (EU), and FPS (UK). International wire via SWIFT. Real-time payment rails where available.

  • KYC/AML and Compliance Engine

Identity confirmation, PEP and sanctions screening, AML transaction tracking, reporting of suspicious activity, and creation of audit trails.

  • Lending and Loan Management Software

Loan origination workflow, credit scoring integration, loan disbursement, repayment scheduling, interest accrual, and collections management.

  • PayFi with Crypto and FIAT

A dual-rail treasury layer that allows customers to hold, move, and spend both fiat balances and stablecoin holdings from the same account interface.

  • AI-Powered Fraud Detection

Real-time unusual activity is detected by machine learning models based on transaction patterns using behavioral biometrics, velocity checks, and geolocation discrepancies.

  • AI-Driven Financial Advisor

Personalized financial insights are produced using user data, including budget overage alerts, savings goal tracking, and spending pattern analysis.

  • Customer Support and Dispute Management

In-app chat, dispute filing for card transactions, chargeback initiation, and case tracking with admin dashboard access for the neobank operator's support team.

How to Develop a Digital Bank Using a White-Label Platform

White-label neobank development with Clarisco follows a structured delivery process that gets a production platform live significantly faster than a custom build.

Step 1 - Regulatory and jurisdiction scoping

The platform's legal structure depends on the jurisdiction. For example, the EU mandates a BaaS partnership or an EMI license. It should use state money transmitter permits in the United States. The UAE requires CBUAE or DIFC/ADGM frameworks. Clarisco scopes this out in the first call.

Step 2 - Platform configuration and brand customization

The white-label platform is then customized based on the client's requirements and initial discussion, and crypto features are enabled or disabled based on the project scope.

Step 3 - KYC/AML and compliance integration

Identity verification vendors (Jumio, Onfido, or Sumsub) are integrated for the document and biometric checks required by the jurisdiction. AML monitoring is configured with alert thresholds and SAR reporting workflows.

Step 4 - Testing and audit

Complete quality assurance for card transactions, payment flows, KYC edge cases, and administrative tasks.

Step 5 - Soft launch

Do it with an initial user cohort to validate transaction volumes and compliance flag rates before full marketing-led acquisition begins.

The Cost of Building a Neo Banking App

Build Type

Development Cost

Timeline

White-Label Neobank

$50,000 - $150,000

4 - 8 weeks

Crypto-Integrated Neobank

$100,000 - $250,000

8 - 14 weeks

Lending-First Neobank

$80,000 - $200,000

8 - 16 weeks

Multi-Jurisdiction Enterprise Platform

$200,000 - $600,000

3 - 6 months

Top 5 Latest Trends in Neo Banking Solutions

  1. Crypto and PayFi Integration

Stablecoin transactions reached $7.2 trillion in February 2026, exceeding ACH for the first time. The GENIUS Act (US, May 2026) and MiCA (EU) have defined the regulatory framework for neobanks that possess stablecoins. Neobanks integrating USDC and USDT as first-class account currencies are capturing the younger demographic that wants one financial app for everything.

  1. AI-Powered Lending Software

Traditional credit scoring fails the underbanked. Neobanks with proprietary AI lending models are reporting approval rate improvements of 20% to 35% versus bureau-only scoring, with equivalent or lower default rates on the additional approvals.

  1. Embedded Loan Management Software

Leading neobanks are embedding BNPL, revolving credit, and SME lending directly into the account experience, with loan origination triggered from within a payment or purchase flow rather than through a separate application.

  1. Agentic AI Financial Management

AI agents that proactively manage finances on behalf of the customer are negotiating better rates, paying bills before due dates, and flagging unwanted services. DeFAI (Decentralized Finance + AI) is extending this to on-chain treasury management for crypto-integrated neobanks, with AI agents.

  1. Super App Expansion

Neobanks are expanding beyond banking. Insurance, stock trading, cryptocurrency, payroll, and loyalty programs are being included as in-app features. The revenue model diversifies from interchange and net interest margin to fee income across multiple financial product categories.

Why Choose Clarisco as Your White-Label Neo Banking Solutions Provider?

Clarisco Solutions is a leading white-label neo-banking software development company. We build feature-rich digital banking platforms for fintech startups, financial institutions, and non-bank operators entering the market.

It covers core account management, multi-rail payment infrastructure, virtual and physical card issuance, AI-powered fraud detection, lending and loan management software, PayFi with USDC/USDT support, and compliance built to jurisdiction-specific standards.

Clarisco's white-label neobank platform is a customizable production platform that has been adapted for consumer banks, business neobanks, crypto-integrated deployments, and BaaS multi-tenant platforms. For businesses evaluating white-label neo banking solutions, Clarisco's engagement starts with a scoping call.

Final Words

The industry pioneers such as Nubank, Revolut, Chime, and Monzo are demonstrating at scale that digital banking wins on cost, features, speed, and user experience. Given that BaaS partnerships remove the necessity for a full banking license, the market structure is created.

A white-label neobank solution from Clarisco will launch in a few weeks. The brand, the clientele, and the revenue structure - all are yours. Start building today.

Frequently Asked Questions

A standard white-label neobank deployment with core account management, card issuance, payment rails, and compliance for a single jurisdiction costs $50,000 to $150,000 in 4 to 8 weeks. A neobank with crypto integration that offers PayFi and supports USDC/USDT requires $100,000 to $250,000 over a period of 8 to 14 weeks. A lending-focused neobank featuring loan origination and AI-driven credit scoring ranges from $80,000 to $200,000. Clarisco offers detailed cost estimates tailored to your specifications.
With Clarisco's white-label neobank software, a standard single-jurisdiction deployment is live in 4 to 8 weeks. The core platform is pre-built and production-tested; the timeline is driven by brand configuration, banking partnership setup, and KYC/AML vendor integration, not by building core banking infrastructure from scratch.
A neobank is a digital-first bank that operates without physical branches, built on modern cloud infrastructure and delivered through a mobile app. A white-label neobank is a digital banking service utilizing licensed, pre-existing software instead of custom-developed technology. The customer experience is identical, and the difference is on the operator side.
Not necessarily, and in most cases not immediately. The typical model for new neobank operators involves a BaaS collaboration with a licensed bank, which manages customer deposits, provides cards through a BIN sponsor agreement, and upholds the main regulatory connection. The neobank operator oversees the customer experience, brand image, and product setup.
Clarisco Solutions has built production neobank platforms across consumer, business, crypto-integrated, and lending-first segments with the full stack delivered as a configurable white-label product rather than a reskin. The initial stage involves a scoping call to establish jurisdiction, the scope of features, and the needs for banking partnerships prior to commencing any development work.

We'd Love To Hear From You!

Know your requirement, our technical expert will schedule a call and discuss your idea in detail. All information will be kept confidential.

Contact Us

Loading...

Skip the queue and book a call with our Founder

Founder
Priyadharshini Suriyanarayanan

Founder & CEO, Clarisco Solutions Private Limited

12+ years in AI, Web3, and enterprise software delivery. Led 650+ product launches across AI agents, generative AI, tokenization, crypto exchanges, DeFi, and NFT platforms. Specializes in AI-driven Web3 product engineering and regulation-ready system architecture.

Halloween GIF